
From logo to lifestyle: what really drives the branded residence premium
The global rise of branded residences goes well beyond the logo, with hospitality and lifestyle icons fighting it out to sate the demand for evermore rarefied offerings across amenities, design, wellness, sustainability, community—and emotional resonance. We tap leading agents to examine the brand power of property.
Explore branded residences for sale
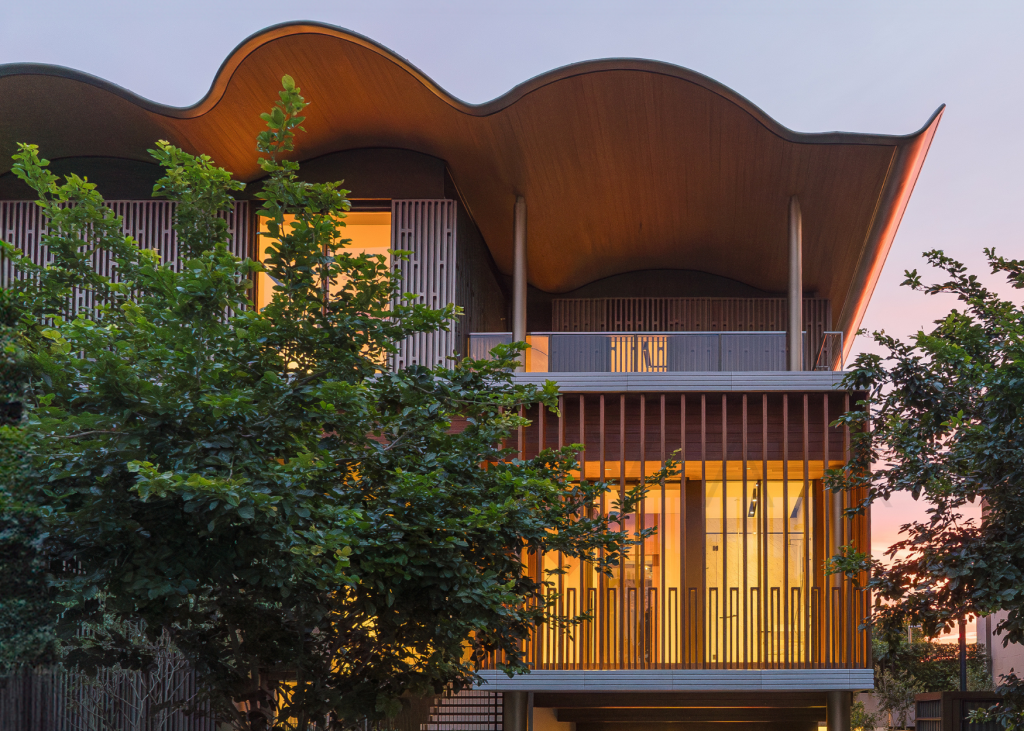
The Six Senses Residences, Bangkok, feature 3 to 5 bedroom villas.
South-east Asia surging
Leong Boon Hoe, founder & CEO, Arcadia Consulting
“Branded residences speak to a modern buyer’s desire for trust, taste, and time well spent. In today’s uncertain landscape—economically and geopolitically—buyers are looking for more than just square footage. They want certainty of delivery, consistency in quality, and an emotional connection.
“In Southeast Asia, three key trends stand out. Vietnam has long been overlooked, but is now surging, with the arrival in Danang of The Residences at Mandarin Oriental and Nobu Residences. Bangkok is reasserting itself with brand-led high design like Porsche Design Tower and Six Senses Residences The Forestias—tailored for regional UHNWIs seeking distinction.
“Singapore remains the bellwether of regional demand, with ultra-luxury launches like W Residences Marina View setting benchmarks for urban branded living. These residences outperform not just on price, but on narrative and aspiration, commanding a 20 to 35 per cent premium over non-branded peers. And as brand-managed rental programmes become more sophisticated, we see more investors calculating in potential returns—not just resale uplift, but operational yield.”
Read Leong Boon Hoe’s market report.
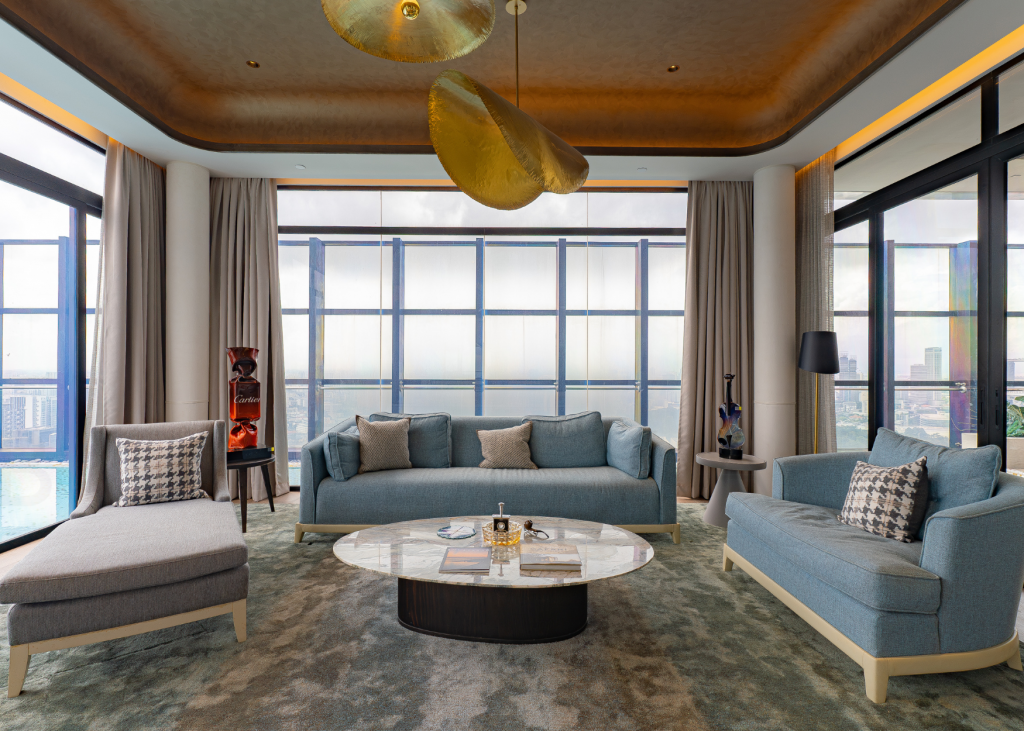
The Ritz-Carlton Residences, Singapore features 4-bedroom condos and a penthouse.
Brand investability
Tricia Ang, vice president, CBRE Singapore
“From an investment standpoint, branded residences typically out-perform during market downturns, as affluent buyers gravitate toward recognisable names that hold resale value better and offer higher rental yields, especially to international tenants who trust global brands.
“The buyer demographic has broadened significantly in Singapore. Traditionally, branded residences were favored by UHNW individuals and foreign investors looking for trophy assets. Today, there’s a notable increase in family office buyers and younger affluent professionals who prioritise integrated lifestyle offerings, wellness-focused amenities and prestige address recognition. Many are seasoned global travelers accustomed to five-star hospitality standards, and now seek the same experience at home.
“Hospitality-led partnerships, particularly with ultra-luxury hotel brands, consistently perform the best. But a truly outstanding branded residence distinguishes itself through uncompromising service standards, architectural excellence and design identity, world-class amenities rivalling the best resorts (spa, wellness retreats, private clubs) and exclusivity and low-density living. Against non-branded ultra-luxury residences, those developments command an average premium of 10 to 20 per cent.
“The appeal of a branded residence extends well beyond its logo. The reputation of the brand is only as strong as the management team ensuring a flawless living experience year after year.”
Read Tricia Ang’s market report.
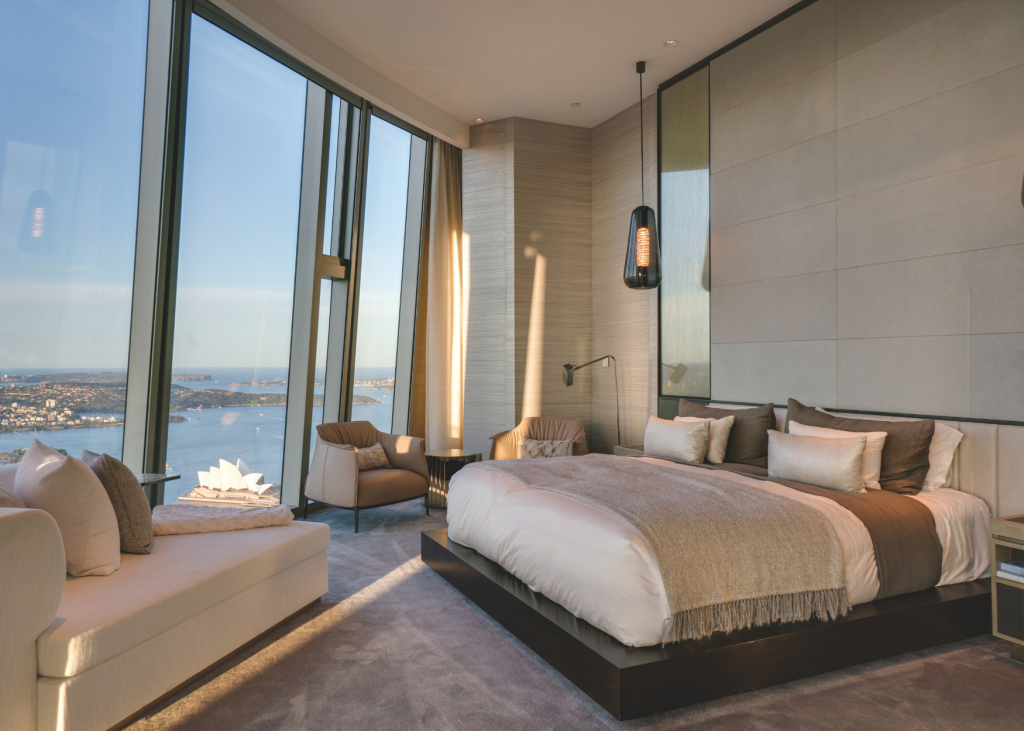
One Barangaroo Crown Residences, Sydney, Australia, features a 6-bedroom penthouse.
Australia awakens
Luke Hayes, director, Colliers Australia
“In the Australian market there’s a lot of education to be done about branded residences. Many people probably don’t have the same level of attraction to or familiarity with the brands as they might overseas, particularly in Asia and Europe. But I believe the demand is there, and One Barangaroo Crown Residences was the perfect example of that—it was a huge success. I think in places like Queensland, it could also be successful, as it would serve as a second home for many. In fact, there are a couple of conversations happening in Queensland where we’re discussing possibilities, exploring the concept, and considering which brands might be a good fit.
“We’ve also had discussions in Sydney about creating a branded residence without an actual hotel—but would there still be a premium purely because of the brand? That’s something we’re debating, but we feel you would need to have the hotel service; the brand on its own probably isn’t enough. Services and amenities are increasingly important, especially in the health and wellness space.
“If we look at Crown Residences, and where we estimated the initial price growth compared to the non-branded market, we were probably seeing about a 20 to 25 per cent increase in values—and that’s translating into resale as well. The demand is there, but it’s about selling the service and offering, and then educating people on how the brand can enhance that experience.”
Read Luke Hayes’ market report.
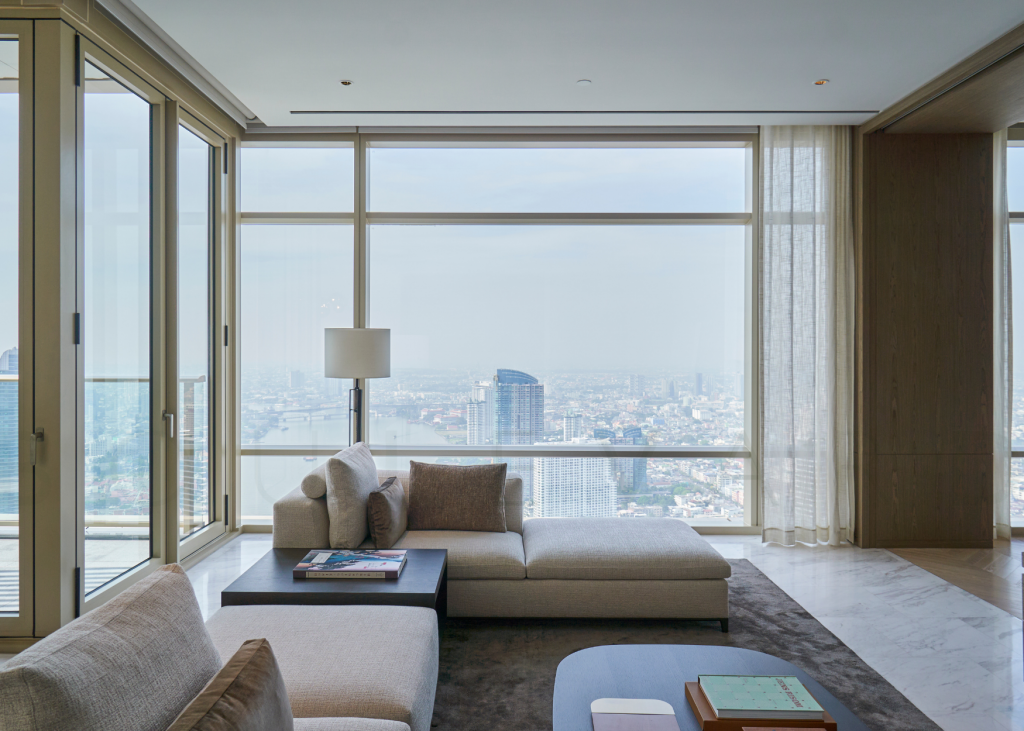
Four Seasons Private Residences, Bangkok, Thailand, features 1-5-bedroom condos and a penthouse.
Battle of the brands
Vimol Kogar, principal, Bangkok 101
“Asia tends to focus on brands that buyers personally identify with. Currently, among the most popular names in markets like Vietnam and Thailand, are Nobu, Four Seasons and Six Senses. But lifestyle brands like Aston Martin and Mercedes-Benz are aggressively pushing new projects in Asia, and I believe that by 2026 there will be an all-out turf war to see who will win the “battle of the brands” in the region.
“The facilities battle is already in full swing. Everything from spas, indoor golf driving ranges, conference facilities and full pet care services—including pet spas, grooming, and healthcare—are becoming common features in branded residences. In summary, branded residences will see a renaissance in the next few years, and interestingly, the players in this sector will be predominantly based in the UAE and Thailand. With the skill-sets we already possess and will continue to attract in the future, Asia will be the place to be for new developments in branded residences. As the branded residences renaissance develops over the next few years, I think the players in this sector will be predominantly looking to the UAE and Thailand.”
Read Vimol Kogar’s market report.
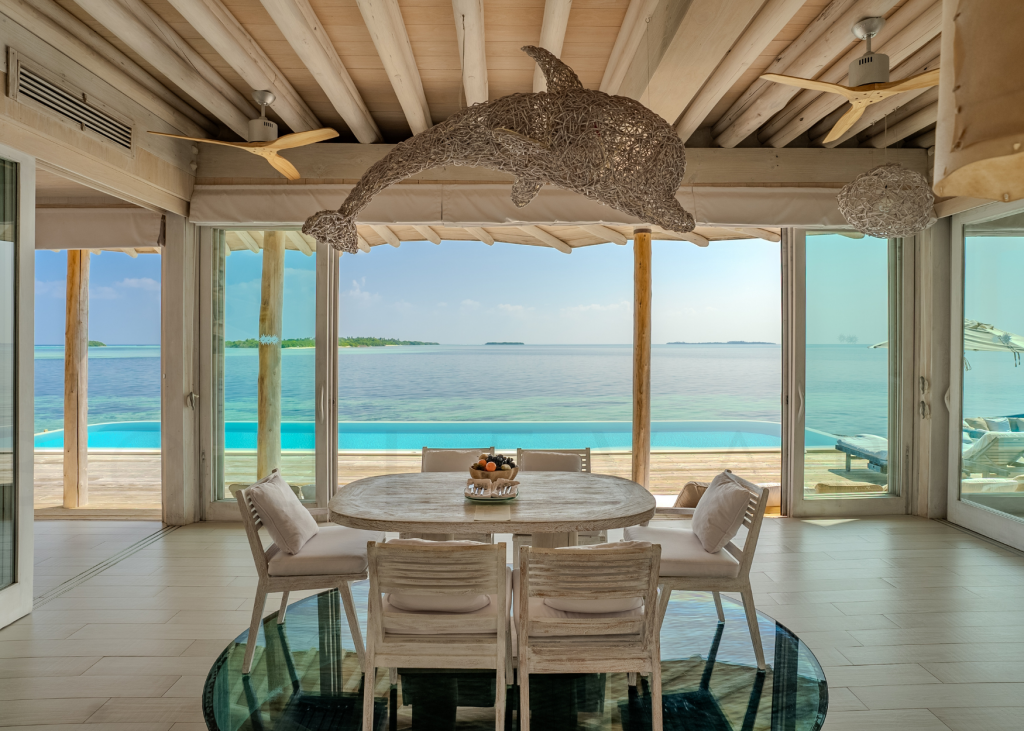
Soneva Jani, Medhufaru Island, Maldives, features 1-4-bedroom overwater and beachside villas.
Lifestyle returns
Lynn Villadolid, founder & CEO, Lifestyle Capital Partners
“Branded residences offer more than just real estate; they deliver a lifestyle underpinned by trust, service, and global recognition. For UHNW buyers, they provide ease of ownership, prime locations, and the assurance of a consistent, elevated experience. Compared to non-branded luxury homes, they command a price premium driven by access to five-star amenities, bespoke services, and the brand’s cachet. Forbes puts that premium at 25 to 35 per cent.
“This premium is backed by performance: branded residences tend to generate stronger rental yields, higher resale liquidity in favourable market conditions, and greater long-term capital appreciation. Location tends to determine variance from this average, with branded properties in major global cities commanding a 24 per cent premium, resort destinations a 32 per cent premium, and emerging cities reaching up to 52 per cent—this is in the Asian region. These tend to be influenced by local market dynamics.
“What has evolved most is the expectation: buyers no longer see branded residences as just real estate with a logo, but as an extension of their personal brand and lifestyle. The emotional return is as important as the financial one. Sustainability and wellbeing, once considered bonus features, are now non-negotiables for many younger UHNWIs. Buyers are driven by how it feels and the authenticity they’ve experienced, being in a like-minded community, and above all, being values-driven.”
Read Lynn Villadolid’s market report.
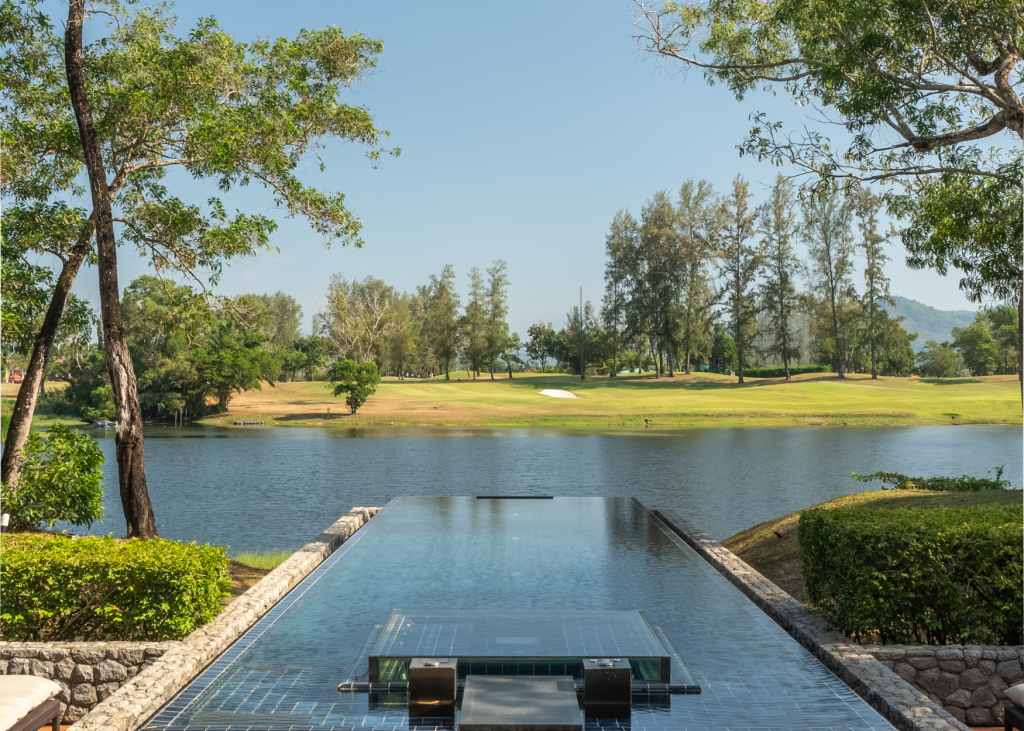
Banyan Tree Residences front onto the golf course in Phuket.
Scarcity sets the price
Otto Twist, Southeast Asia director of International Residential Sales, Savills
“Across the region the premium a brand commands has moved from 23 to 29 per cent over the past year, which still leaves it short of the global average of 33 per cent. Established cities like London and New York set a ceiling Southeast Asia has not reached. What is closing the gap is not more product but less of it: if you’re to command the price premiums we’re talking about, there’s only a certain number of buyers globally who are going to pay for it.
“Banyan Tree Beach Residences Oceanus, Phuket, Thailand. (Photo courtesy of Savills Singapore)
Sub-50 really is where people, particularly in the urban resorts, get the scarcity value that really drives the premium. Aman Singapore is arriving with fewer than 30 Sky Villas on top of the country’s tallest residential building, and the Mandarin Oriental at Bai Nom in Vietnam will have 25 residences. Singapore has only ever completed three or four branded schemes. It’s really scarcity that’s driving price growth there.
“The brand on the building is the operator, not the developer, and the length of its agreement matters as much as its name. If it’s a five- to 10-year agreement, then suddenly in 10 years it may not be a hotel brand operating anymore. Established operators are trading well on their record; newcomers without one are struggling to get either the results or the premiums. In the high-growth markets I would go and stand on the site rather than trust a brochure or a floor plan. Your instincts usually give you a pretty good idea whether it’s going to be delivered or not.”
Read Otto Twist’s market report.
Read next:
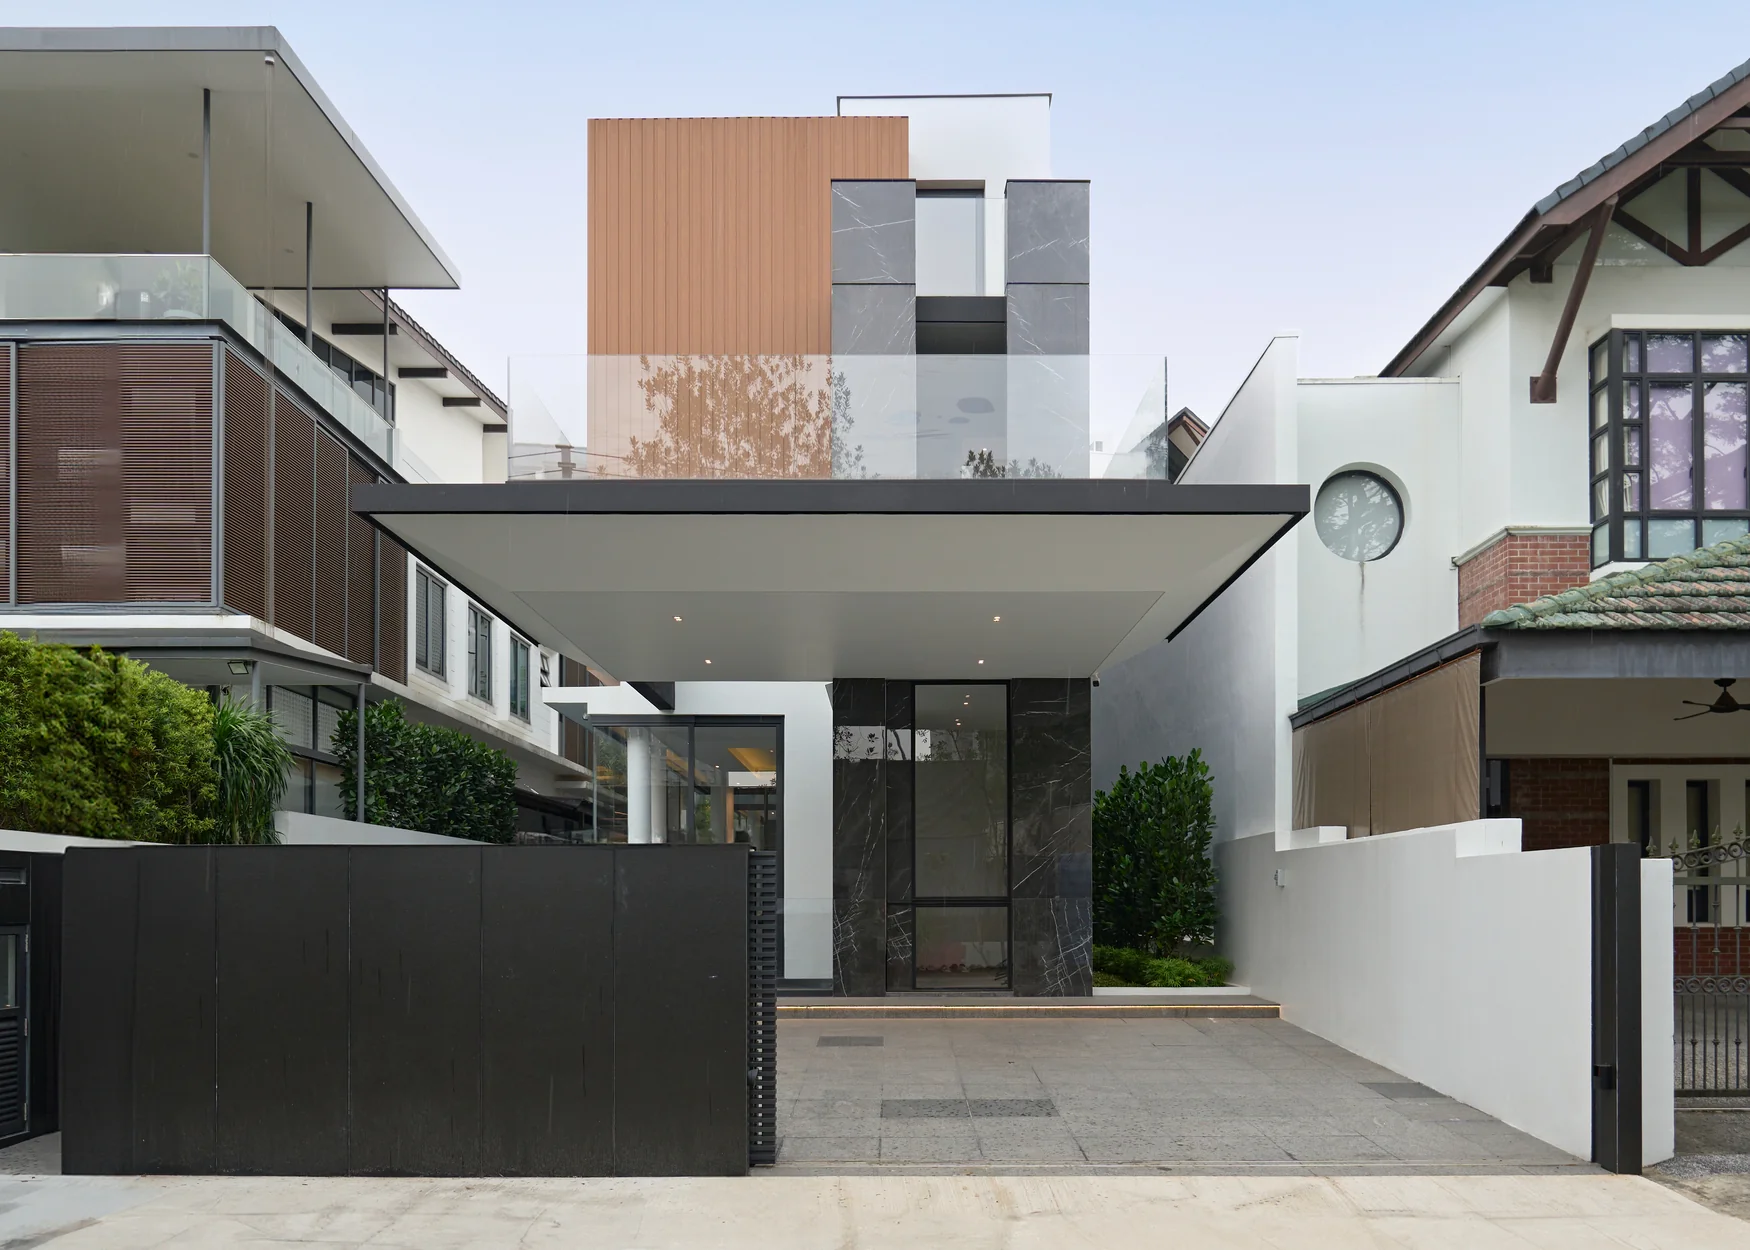
8+1 bed | 10,200 sqft area 19,500,000 SGD
5 bed 19,380,000 SGD
4 bed | 4,208 sqft area POA
3-8 bed | 699,654 - 784,080 sqft area POA
6 bed POA